


We all know the midlife reinvention story. And the subsequent glow up.
You leave the controlling narcissistic husband.
Lose 15 pounds.
Get cool, wispy, sexy bangs.
Six to twelve months later, you’re drinking a spritz in Italy with a hot new boyfriend, talking about finally choosing yourself.
Oh, and you have abs now. And all of your wrinkles have gone away. And you look hot AF.
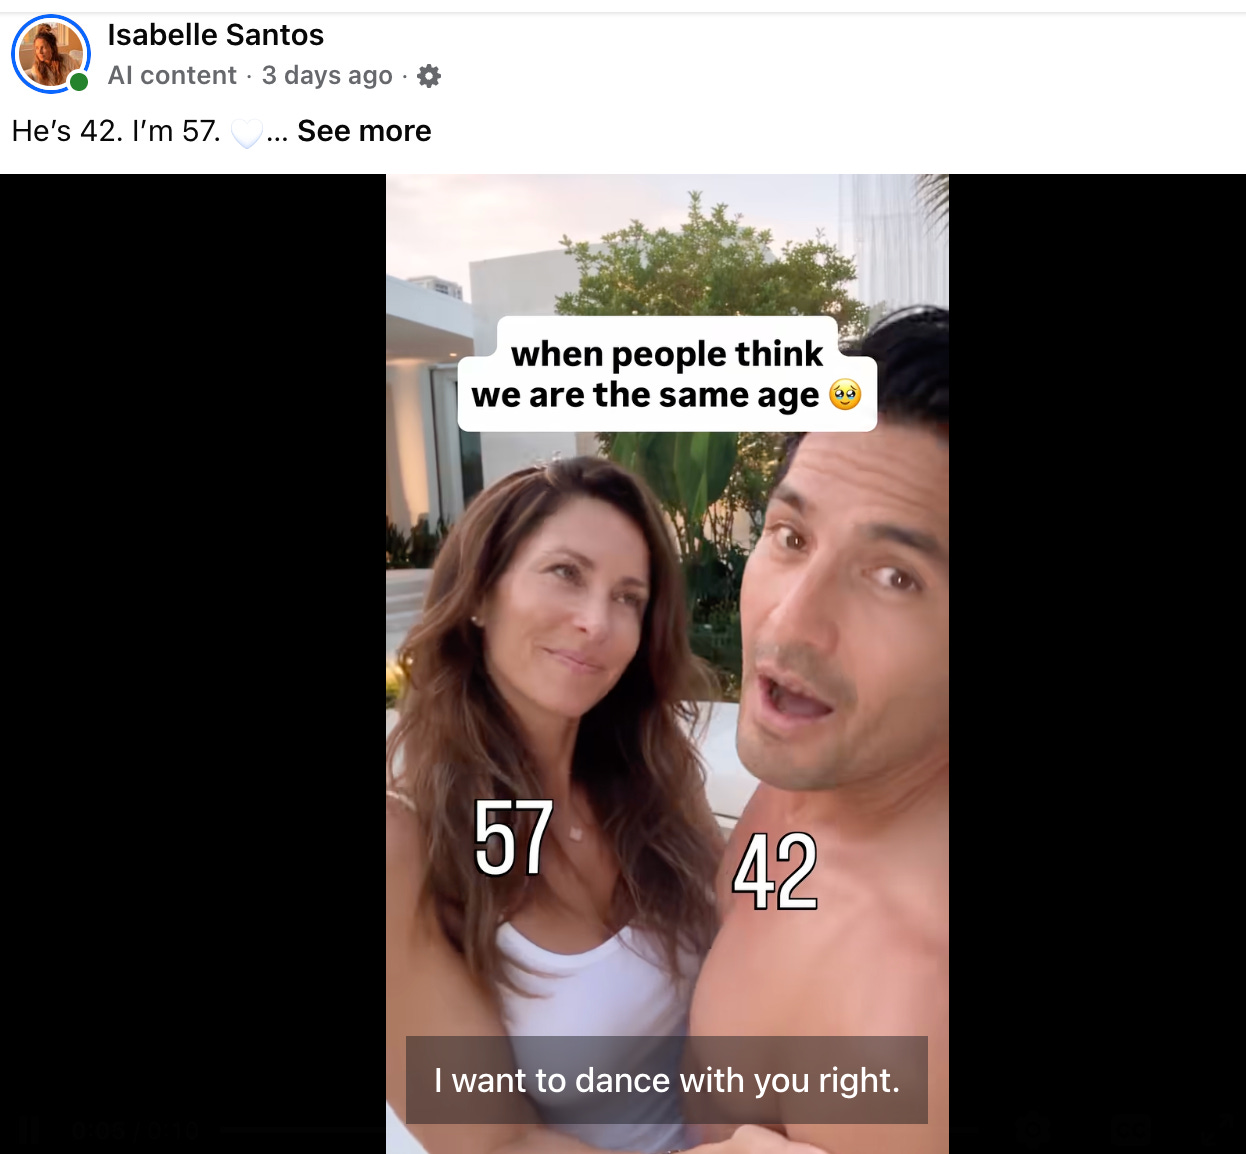
Who doesn’t love this story? Who doesn’t want this story? It’s marketed to us everywhere. Not just by fake AI women, but in the highlight reels of real women living out their fabulous midlife reinventions all over social media.
We’ve romanticized midlife reinvention into one giant glow-up. One giant upgrade where you emerge hotter, happier and somehow with significantly better hair than you had during your entire marriage.
Because you’ve finally “chosen yourself.”
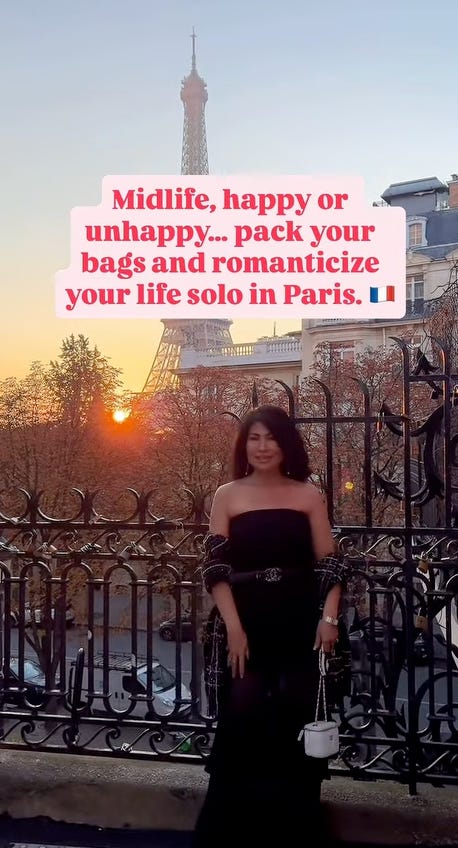
Next thing you know, you’re wandering the streets of Paris in a $2,000 outfit, drinking wine at 2 p.m. and looking pensively into the middle distance.
I’m all for it. I am really am.
I just have a few unsexy questions:
Where are you living? Can you afford the house on one income? Who paid the divorce lawyers? What happened to your health insurance?
And who exactly is financing the upkeep on your new cool, wispy, sexy bangs? The Pilates. The facials. The 10 supplements you take before breakfast? All your new clothes?
Whether you’re blowing up your entire life or just giving it a really good glow-up, there’s one part nobody seems particularly interested in romanticizing: the money
Midlife reinvention can get expensive at exactly the moment your financial life may be getting smaller.
You’re downsizing the house, the marriage, the career, maybe your entire life. Meanwhile, your fabulous new life has an entirely new cost structure.
I recently read Midlife Reinvention: Traps, Tropes, and Truths by Cheryl Wischhover, which I absolutely loved. Then I found myself reading and rereading Let’s Not Lie to Ourselves by Laura LeBleu on her Geezer Magazine Substack.
And my head started spinning about all the women I know who are somewhere in this “reinvention” phase of their lives.
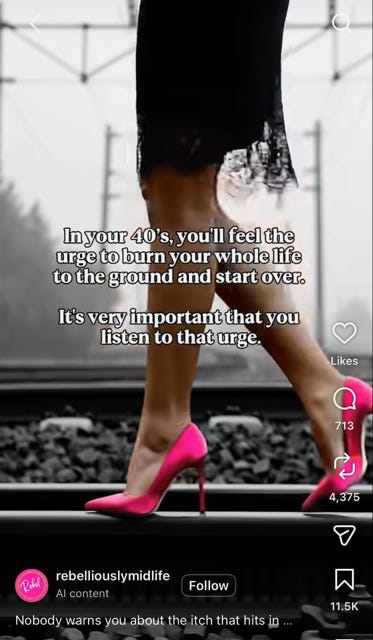
Instagram makes midlife reinvention look very glamorous. It does the same thing with facelifts. You see the before and the fabulous after. You don’t see much of the messy shit in between.
The social media midlife carousels are the highlight reels of a comeback tour. You’re walking through the city streets in a chic new outfit looking like you’ve finally figured everything out. And you are “doing what I want” now.
We don’t see the pretty significant financial reckoning that can come with this midlife reinvention.
It’s something I see so many women I know struggling with quietly. As Laura LeBleu put it, Let’s Not Lie to Ourselves. Reinventing your life in midlife can be amazing. It can also be complicated, messy and really expensive.
Reinvention is expensive
I don’t just mean the beauty glow-up. The five-day trip to Korea. Pilates. Hair. New clothes. Maybe the facelift. The cool new solo apartment. And all the new shit you suddenly need because you’re finally living life on YOUR terms.
Recently, a friend in her mid-50s sat down with me because she desperately wants to quit her job and move to another country. She had no idea if she could afford to do either. Oh, and she wants to start saving for a facelift.
Another girlfriend, also in her mid-50s, is thinking about leaving her husband and wanted to know what would happen financially if she literally just left. Where would she live? What could she afford? What would her life actually look like?
Another can technically afford the life she has, she’s just no longer sure she wants to keep working this hard to pay for it. All the shit you accumulate over 25 years starts to feel less like success and more like overhead.
Different circumstances, but really they’re all asking some version of the same question: What would it actually take to change my life?
How exactly do you get from where you are now to “bigger dreams, less explaining” and “building a life that feels like yours?” The general Instagram midlife sales pitch is a little vague on the accounting.
Which is why every time I read one of these midlife glow-up stories on an Instagram carousel, I find myself thinking the same thing:
This all looks fantastic. But I’d like to see the math behind this midlife reinvention.
Did we sell the house? Are we living off savings? Was there a divorce settlement? Did we take a giant pay cut? Are we putting the reinvention on a credit card?
Sometimes the reinvention chooses you.
An unexpected divorce. A financial loss you never saw coming. A career that no longer works. Or maybe you’re just tired of working at the pace required to keep paying for a life you’re not even sure you want anymore.
And that is how helping a few girlfriends with their finances somehow turned into a financial article on a Substack that is ostensibly about beauty.
Before You Ask Why the Facelift Lady Is Giving Financial Advice, Turns Out I Have Actual Qualifications
As I sat down with my aforementioned girlfriends and helped them work through these pretty major life decisions, they both said some version of the same thing to me, “You should put this on your Substack. This is so helpful.”
So, here is a brief explanation of why anyone would take financial advice from the woman who usually writes about facelifts and the best root touch up product ever.
Before Charlotte’s Book, I had another life. I graduated from Cornell with honors in business and economics and spent nearly 15 years at JPMorgan as a top-ranked research analyst. I resigned in 2014.
Then, years later, my own financial life blew up.
At the end of my marriage, my ex-husband lost roughly 70 percent of our net worth in the span of about 24 months. I found out later. I won’t get into the actual dollar amount, but it was a lot and drastically life changing.
I was 41 and had left the corporate workforce six years earlier.
So I’ve had the slightly unusual experience of understanding money professionally and then having to completely reconfigure my own financial life. Which is exactly what I’m watching so many women around me trying to do now: figure out what a new life, will actually look like.
Mine was forced on me. In hindsight, it was one of the best things that ever happened to me. At the time, it was horrific.
So, You Want to Blow Up Your Life?
The problem is, you’ve spent 20 or 30 years building the one you have. Now you have to disentangle it.
What can you afford on your own?
Are your gorgeous, high-maintenance highlights still in the budget?
What does one income afford you?
Where and how do you want to live?
I’ve found beauty maintenance gets more expensive as you get older. Gray hair. HRT. More frequent Botox. Better skincare. Apparently basic beauty maintenance comes with an operating budget that only goes up.
Of course, the most important question remains:
How are we financing the part where you’re suddenly in Positano, 15 pounds thinner, wearing really fabulous linen and having sex with an Italian man 10 years younger?
A lot of women hit midlife and find themselves in what I’ve recently started seeing referred to as “rich poor.”
Not to be confused with “fake rich.” Fake rich is living a life you could never really afford. Rich poor is having built a life you genuinely could afford, until something changes the math.
You have assets. Maybe a beautiful house. Retirement accounts. Two good incomes built the life you’re living. From the outside, you look rich.
But the house has a mortgage. The kids are expensive. Insurance is expensive. Your entire life was built around two incomes or one shared pool of money. Split that household up and suddenly the math looks very different.
So what are the next steps?
Definitely do not start your midlife reinvention with the facelift. Or the solo trip to Paris or an Eat Pray Love through Bali. Not yet at least.
And definitely do not start with a $799 midlife reinvention course.
Let me give you some actual financial advice and tell you exactly where to begin.
Before you do anything, figure out what your life actually costs
It sounds ridiculously basic.
It is also amazing how many people cannot tell you what it actually costs to run their life every month.
You cannot figure out whether you can quit your job, get divorced, move, retire earlier, invest more or blow up your entire life and move to Portugal until you know two things:
How much of my spending is truly fixed?
And: How much of it is variable?
You need to know these two numbers. Here’s exactly how to figure them out:
One quick disclaimer before we get into it: One of my girlfriends told me she was thinking about “hiring a coach” to help her. I practically screamed: PLEASE DON’T WASTE YOUR MONEY. And this is another reason I wanted to write this article.
There are a lot of people online whose advice somehow leads to the shocking discovery that the answer to your problems is their $1,500 course, conveniently marked down from $2,499.
Money is not, in fact, floating around the internet waiting for you to step into your midlife feminine power and receive it. There is no masterclass here. I will not ask you to manifest abundance.
This is not a sales funnel. The only thing I’m going to try to sell you is a $9-a-month subscription to my Substack.
Now, here is the incredibly simple system I use to understand my finances: two personal credit cards. One for fixed expenses. One for variable expenses.
The fixed card is for your recurring basic living expenses. For example, your phone bill. Utilities. Rent. Homeowners insurance. Car insurance. Essential subscriptions or medications. Anything automated and basically non-negotiable month to month goes on this card.
I don’t use this card for anything else. I don’t even carry it with me. I pay the balance in full every month, so I’m not paying interest, but I am collecting frequent flyer miles.
The second credit card is for variable expenses. These are all the expenses completely under your control every month. For example: Hair appointments. Skincare. Makeup. Uber. Amazon. Restaurants. Clothes. Going out. All the random shit you buy that doesn’t seem like very much money individually and somehow becomes a horrifying number at the end of the month.
I put all of that on a separate card.
Why?
Because I want to know two numbers every month: What does it cost to maintain my life? And what am I choosing to spend?
Those are very different numbers.
Do this for three or four months and then take a long, hard look at both numbers and see where you land. Don’t judge it yet. Don’t announce that you’re never ordering Uber Eats again. Don’t start cancelling everything in a panic.
Just know your numbers: Fixed and variable. And if your life changed tomorrow, which of those numbers could you actually change? And what could you change them to?
This is where I start with anyone who asks me for help. Until you understand what’s coming in and what’s going out, everything else is noise. Planning, budgeting and investing come later. Everything starts here.
Once you know and understand these numbers, you can start asking the hard questions:
Can I afford to leave my marriage?
Can I actually afford to quit my job?
Why do I look rich on paper and feel broke in real life?
Do I still want this enormous house, or am I just working to pay for it?
What would it cost to live the life I actually want?
Can I afford to blow it all up and start again?
And, importantly, are the highlights still in the budget? What about those quarterly Botox appointments?
When can I get the facelift?
Can I go to Korea for a glow-up without putting my reinvention on a credit card?
This post was a bit of an experiment. If practical financial advice like this is useful, tell me in the comments. I’ll keep going. Midlife is expensive and confusing enough. We might as well talk about the money too.
If this article sucked, you can tell me that as well. I’ll happily return to my regularly scheduled programming of facelifts, celebrity rants and skincare. Coming next week: how to talk to your husband about getting a facelift. See? Finance and beauty really are connected.
Robin, smart post, and thank you from an almost 76-year-old who's past the blow-up-your-life tropes with a couple of suggestions: A beauty budget definitely does NOT have to increase as you age but we may become more vulnerable to the fear-mongering-marketing aimed at us. My advice: Don't fall for it. (For more on that, go to HNTFUYF, obv.) And a new book by financial advisor Jean Chatsky can be extremely helpful and reassuring: The Forever Paycheck. Worth the $32 investment. x
Incredibly helpful and realistic!